Prior to 18 May, reporting entities conducting customer due diligence (CDD) on trusts were required to verify source of wealth (SoW) and source of funds (SoF) by...

EDD is a deeper, more rigorous form of customer due diligence. It is applied when a client or transaction carries higher risk – for example, politically exposed person (PEPs), complex ownership structures, offshore investors, or unusually large transactions. It’s designed to give reporting entities greater visibility into who they’re dealing with, where the money is coming from, and whether there are hidden risks of money laundering or terrorist financing.
Unlike standard checks, EDD requires gathering and verifying additional layers of information, including Source of Funds (SoF) and Source of Wealth (SoW). These insights allow you to build a clear picture of your client’s financial background, so you can easily identify potential risks, and confidently demonstrate to the supervisor that you understand both the immediate transaction and the broader origins of the customer’s wealth.
At first glance, SoF and SoW can seem interchangeable, since each examines aspects of a client’s financial background. The realitiy is that they answer very different questions: SoF focuses on the specific money being used in a transaction, while SoW looks at the bigger picture of how your client built their overall financial position.
Because of this difference, the supervisor treats SoF and SoW as separate, but complementary requirements. Together, they provide a complete picture that helps businesses demonstrate they understand both the specific funds being used and the client’s broader financial background.
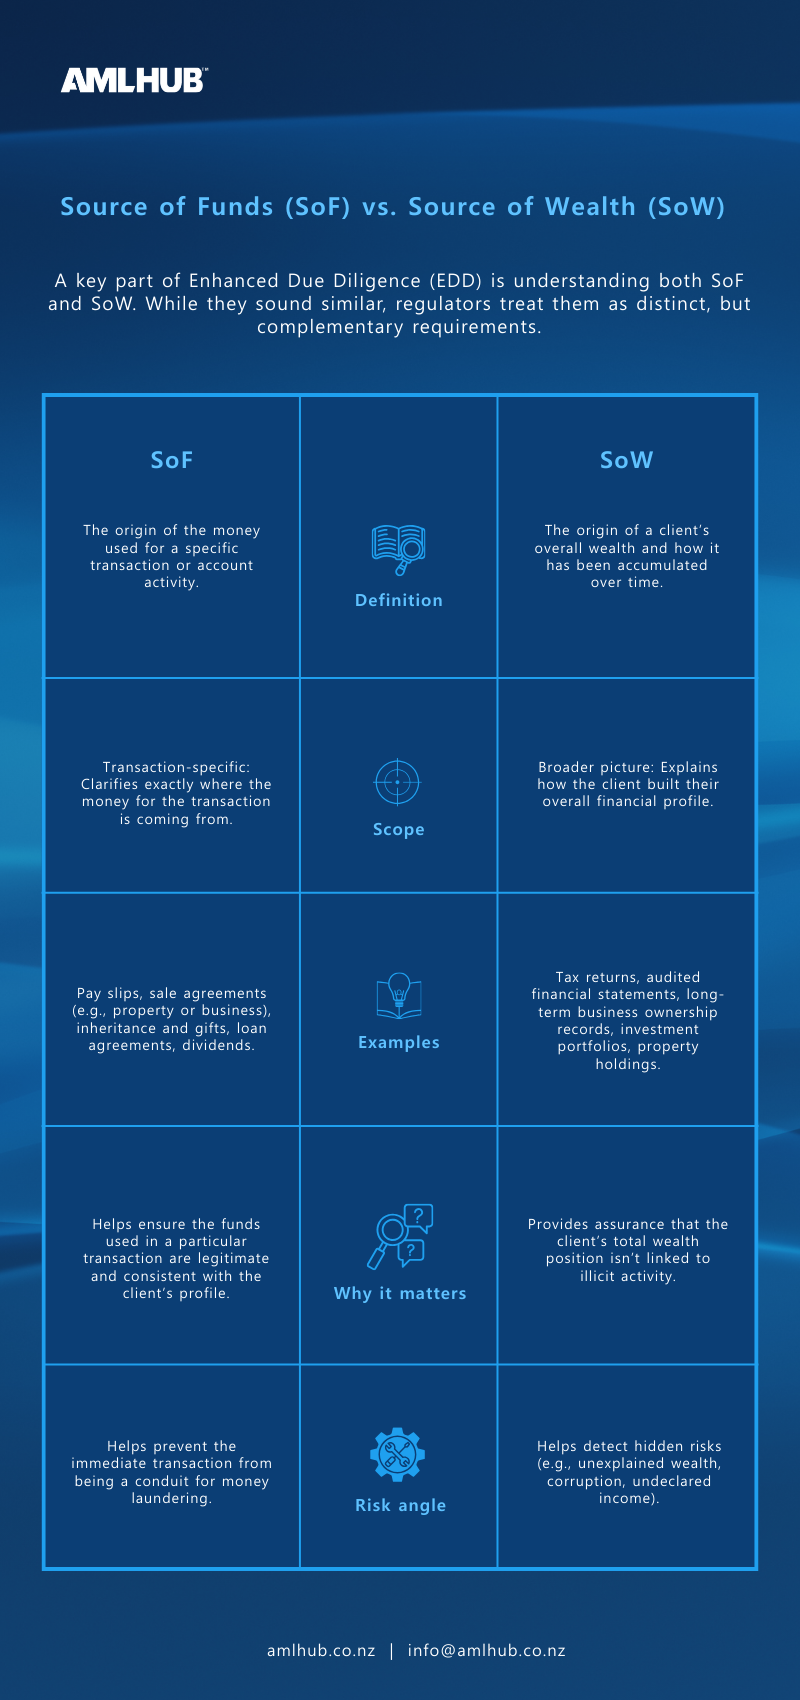
Think of SoF and SoW as two pieces of the same puzzle. For example:
By addressing both aspects, you give the supervisor, and yourself, confidence that your client’s money is clean, consistent, and compliant.
The Financial Action Task Force (FATF) and the supervisor highlight SoF and SoW as critical safeguards for effective AML/CFT programmes. They expect businesses to apply a risk-based approach, so the depth of the client review should match the level of risk. A PEP or client moving funds from a high-risk jurisdiction will attract more scrutiny than a long-standing client with a straightforward profile.
Getting this balance right is about preventing your business from being used for money laundering, protecting your reputation and building regulator confidence.
The challenge, of course, is putting this into practice. Completing these checks thoroughly and keeping records can quickly overwhelm in-house teams, which is where specialist support can make the difference.
Understanding the difference between SoF and SoW is one thing, but collecting, reviewing, and documenting that information is another. Many reporting entities struggle with the practical side: chasing clients for sensitive documents, interpreting complex wealth structures, and ensuring every step meets compliance expectations.
That’s where the AMLHUB CDD Outsourcing team comes in. Our AML compliance specialists act as an extension of your business, handling the most challenging EDD cases from start to finish.
EDD doesn’t need to slow your business down. Our team of AML specialists can manage SoF and SoW checks on your behalf, giving you confidence that your obligations are met, your documentation is thorough, and your client relationships stay strong.
Talk to our outsourcing team today to see how we can help.
Head of Outsourcing
Bek Fazilov is the Head of Outsourcing at AMLHUB Group, with a strong background in AML compliance, complex onboarding and day-to-day operations. He brings a practical, risk-based approach to Customer Due Diligence - focused on clarity, consistency, and uncovering real risk.

Prior to 18 May, reporting entities conducting customer due diligence (CDD) on trusts were required to verify source of wealth (SoW) and source of funds (SoF) by...


Customer Due Diligence (CDD) Outsourcing means handing over some or all your CDD to a trusted partner. Instead of managing the process entirely in-house, you can...